
varclock
The option market's day-by-day variance calendar.
Abstract
Reads from one S&P 500 option-chain snapshot how much volatility the market prices for every trading day, scheduled event and weekend ahead. For volatility traders, derivatives quants and risk managers.
1Motivation
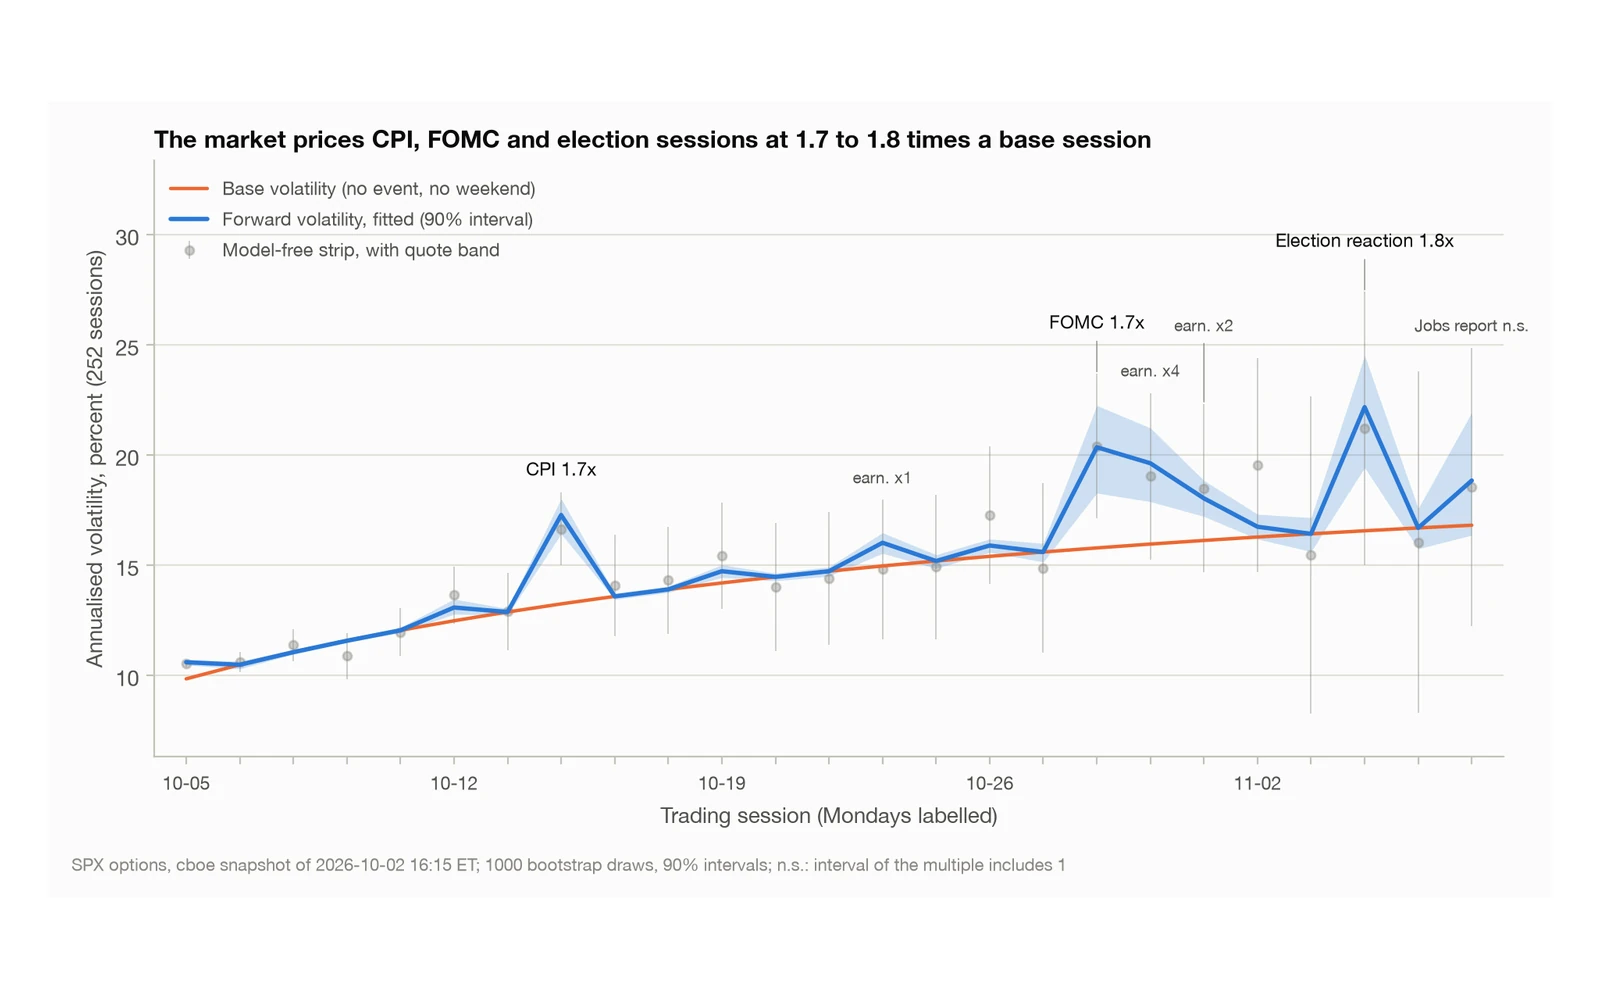
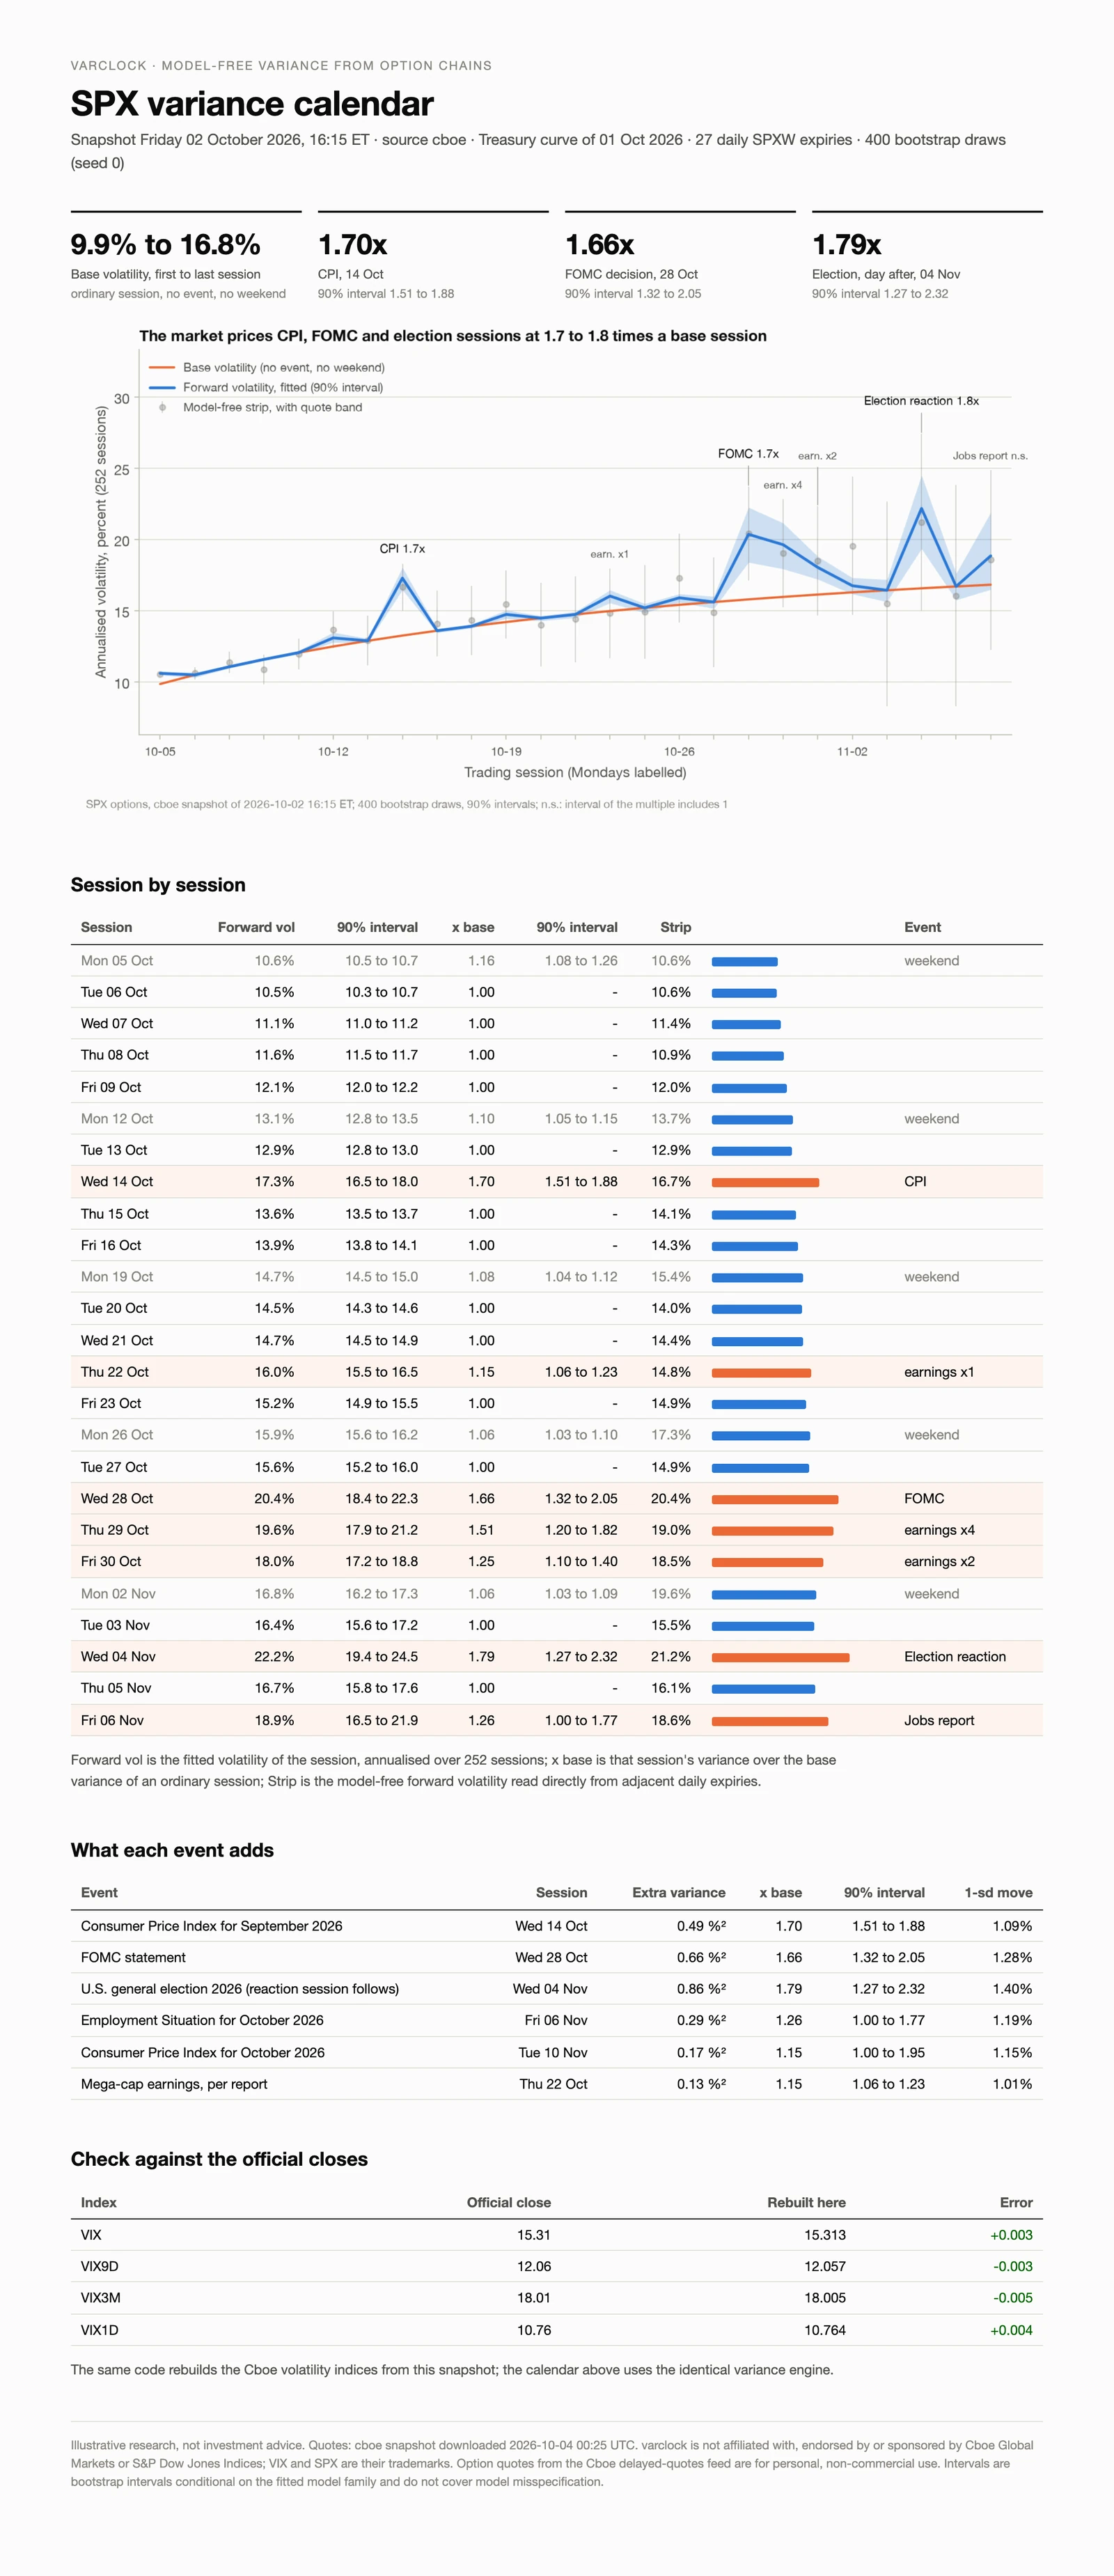
Volatility is not spread evenly over the calendar: weekends carry little, FOMC, CPI and election days carry a lot. Desks track this in spreadsheets; with daily SPX expirations the whole calendar can now be read model-free from one snapshot.
2Method
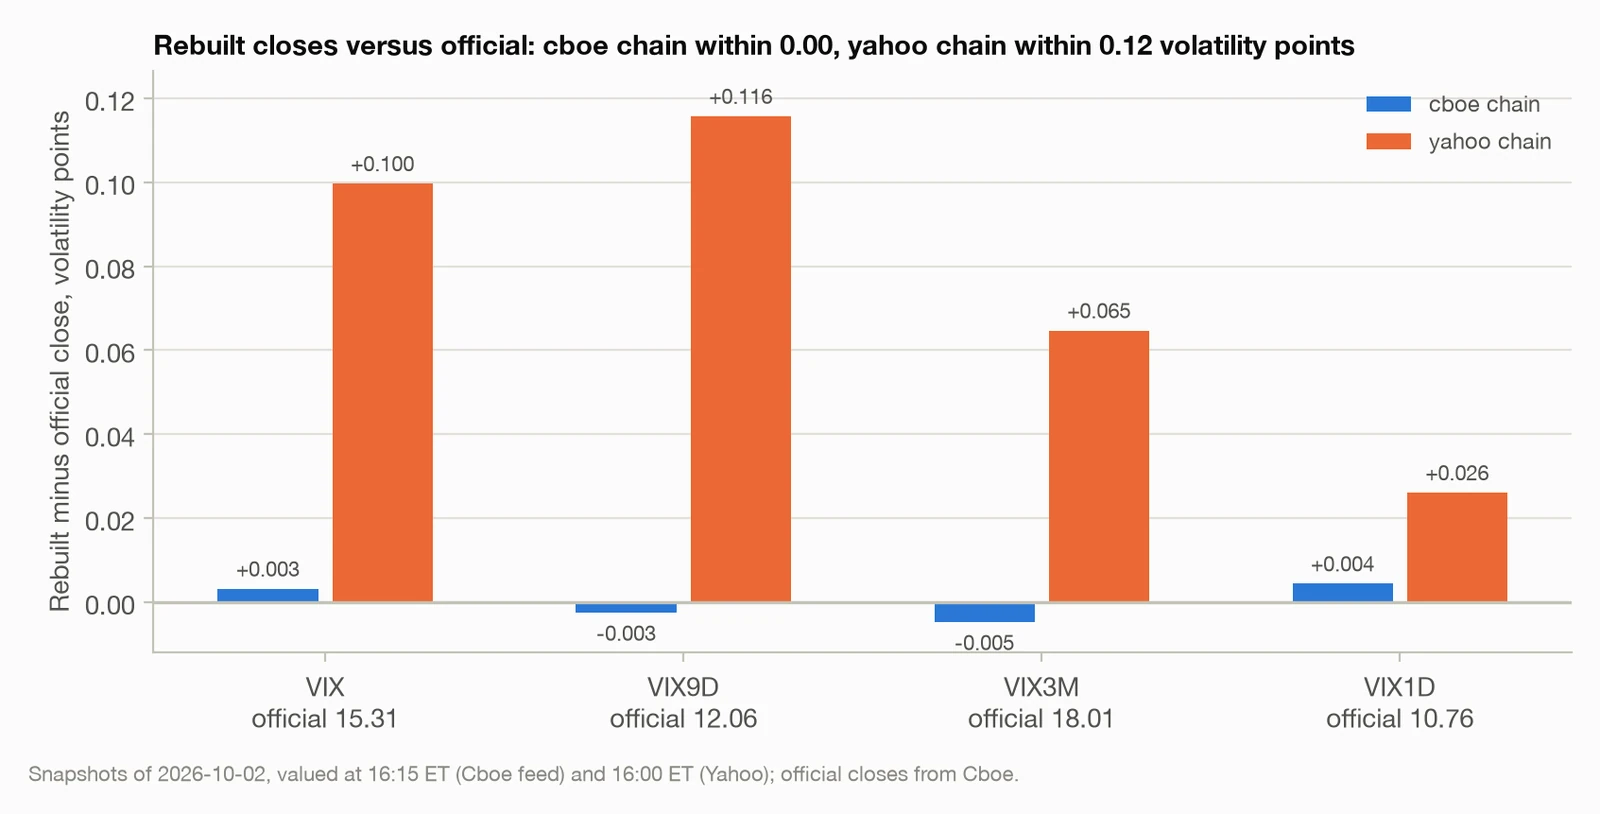
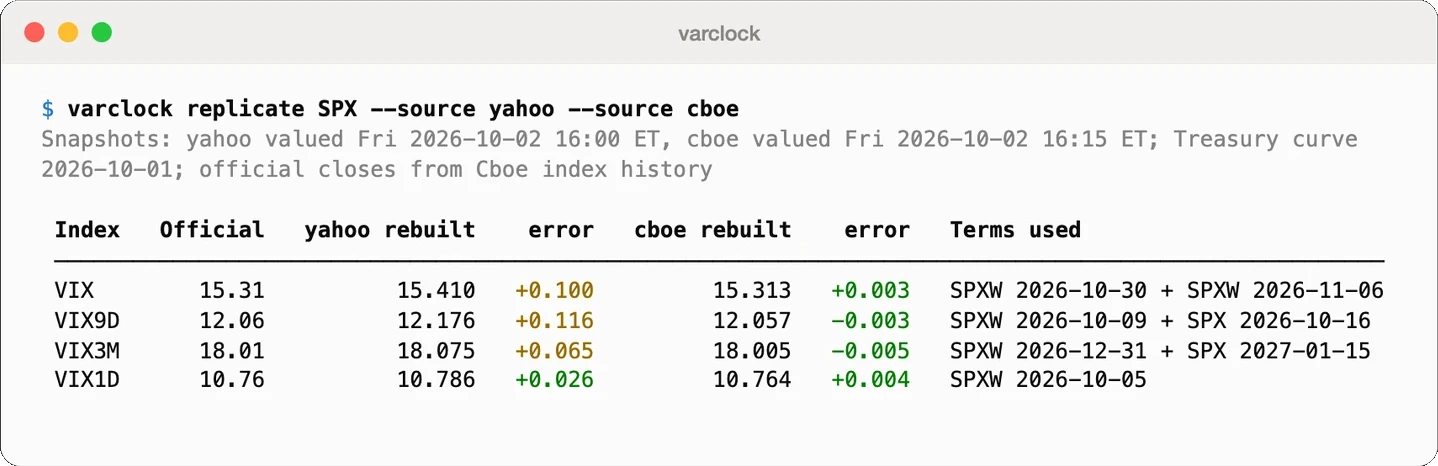
- Model-free variance per expiry following the published Cboe volatility-index methodology, tested against Cboe's worked example and official closes.
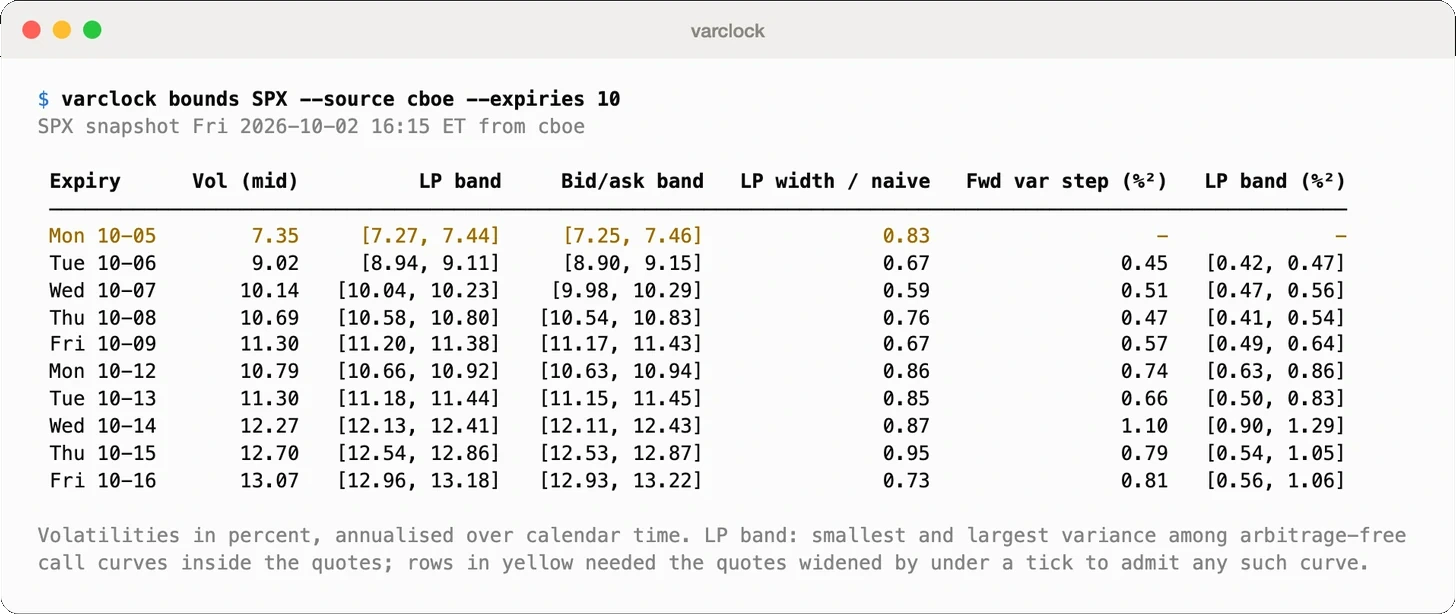
- Forward variance between adjacent daily expirations, with arbitrage checks.
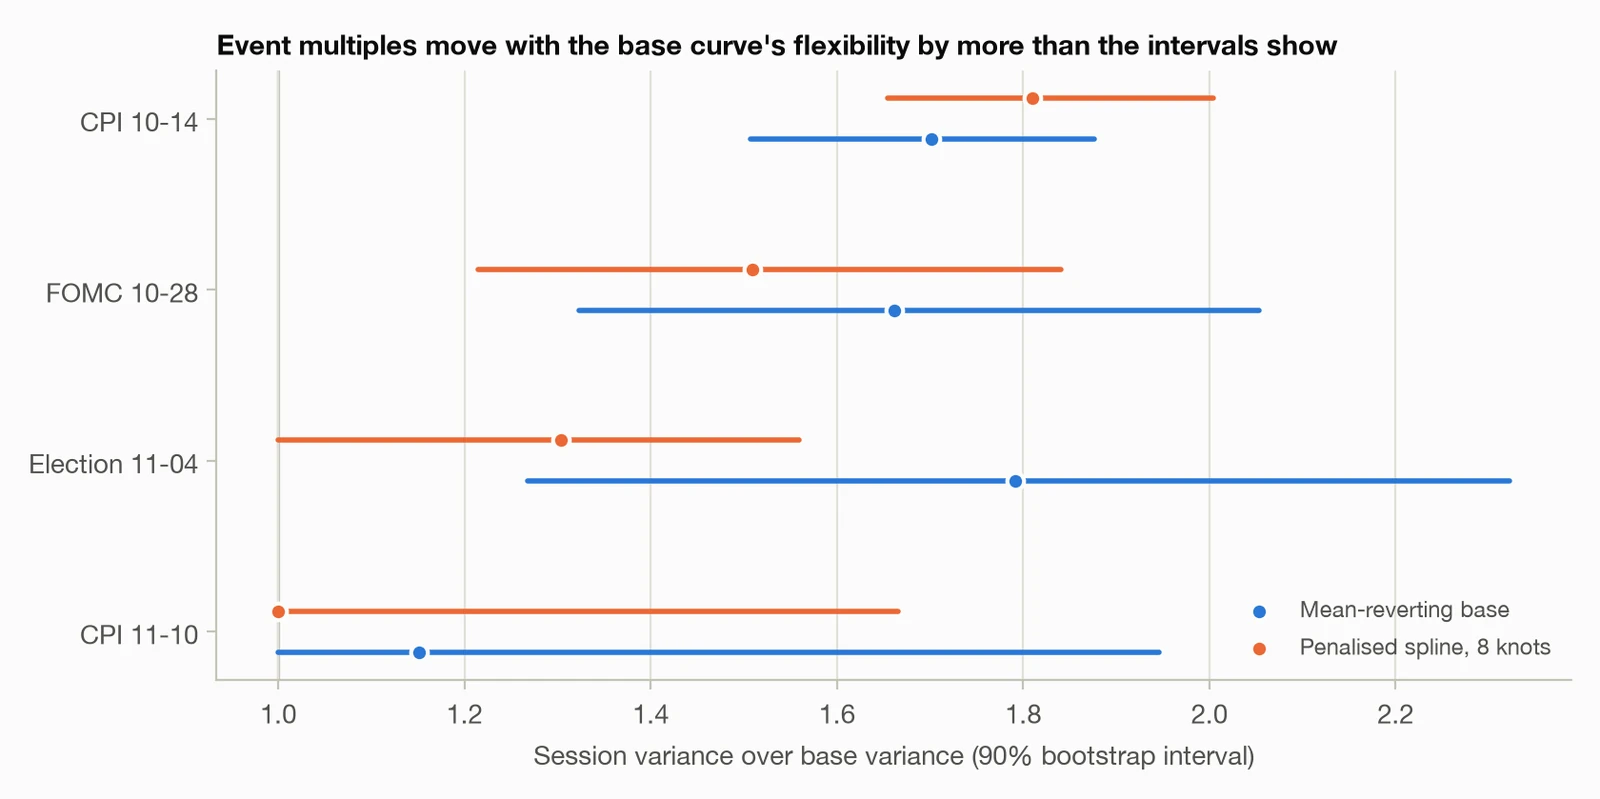
- Fit a smooth base curve plus event bumps and a weekend weight with bootstrap intervals.
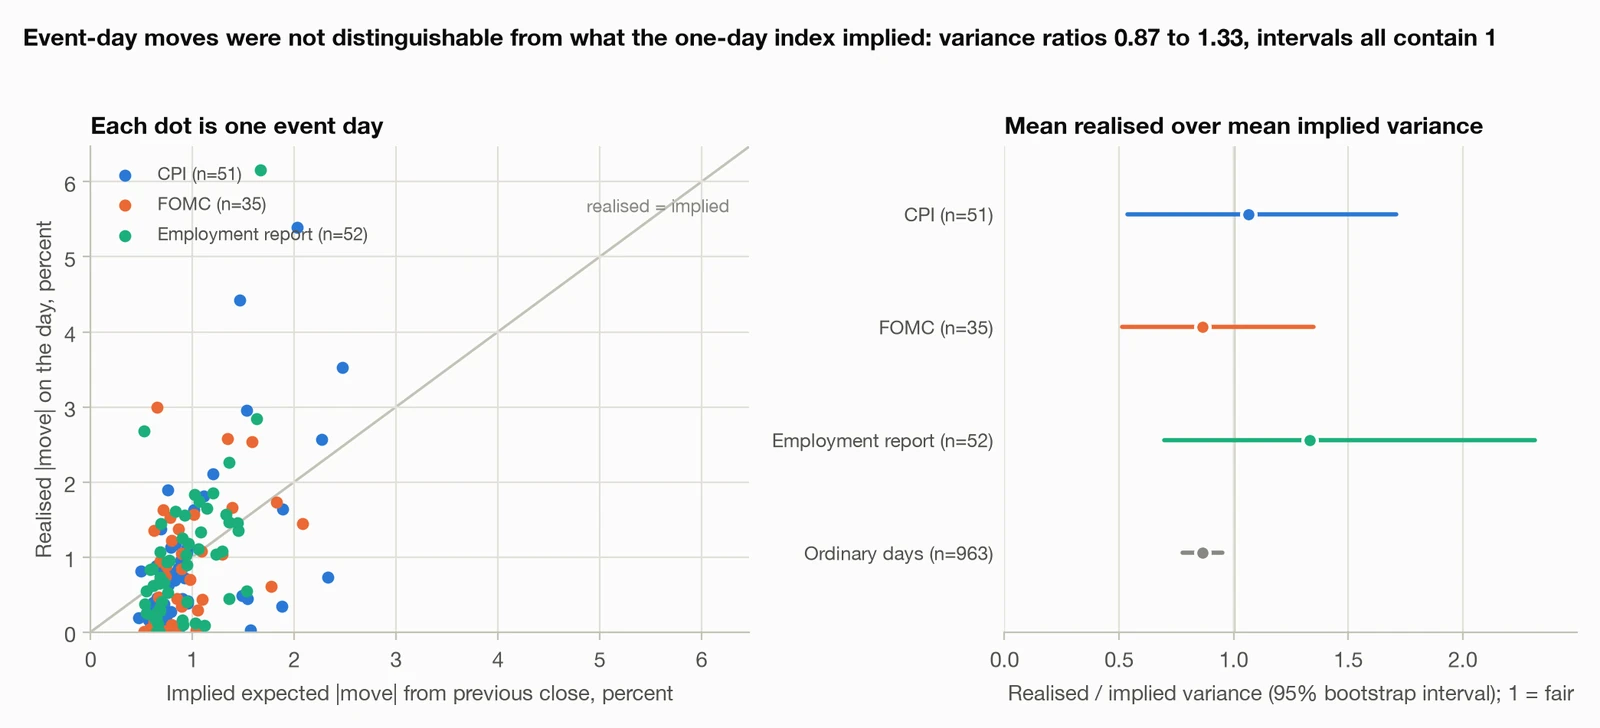
- Compare implied with realised moves on past CPI, FOMC and jobs-report days.
3Results
4Usage
4.1 Variance calendar
Forward volatility per session with intervals and event labels.
varclock calendar SPX4.2 Replicate the indices
Rebuilds the official volatility indices from the same quotes.
varclock replicate SPX --source yahoo --source cboe5Installation
pip install "varclock[yahoo,plot] @ git+https://github.com/Thesimpleex/varclock"Python 3.11 or later. Not on PyPI; installs from GitHub.
6Specification
- Runs
- Python 3.11+, CLI
- Built with
- Python, NumPy, SciPy, rich
- License
- MIT
- Version
- 0.1.0
Source code, issues and releases: github.com/Thesimpleex/varclock. License: MIT.